
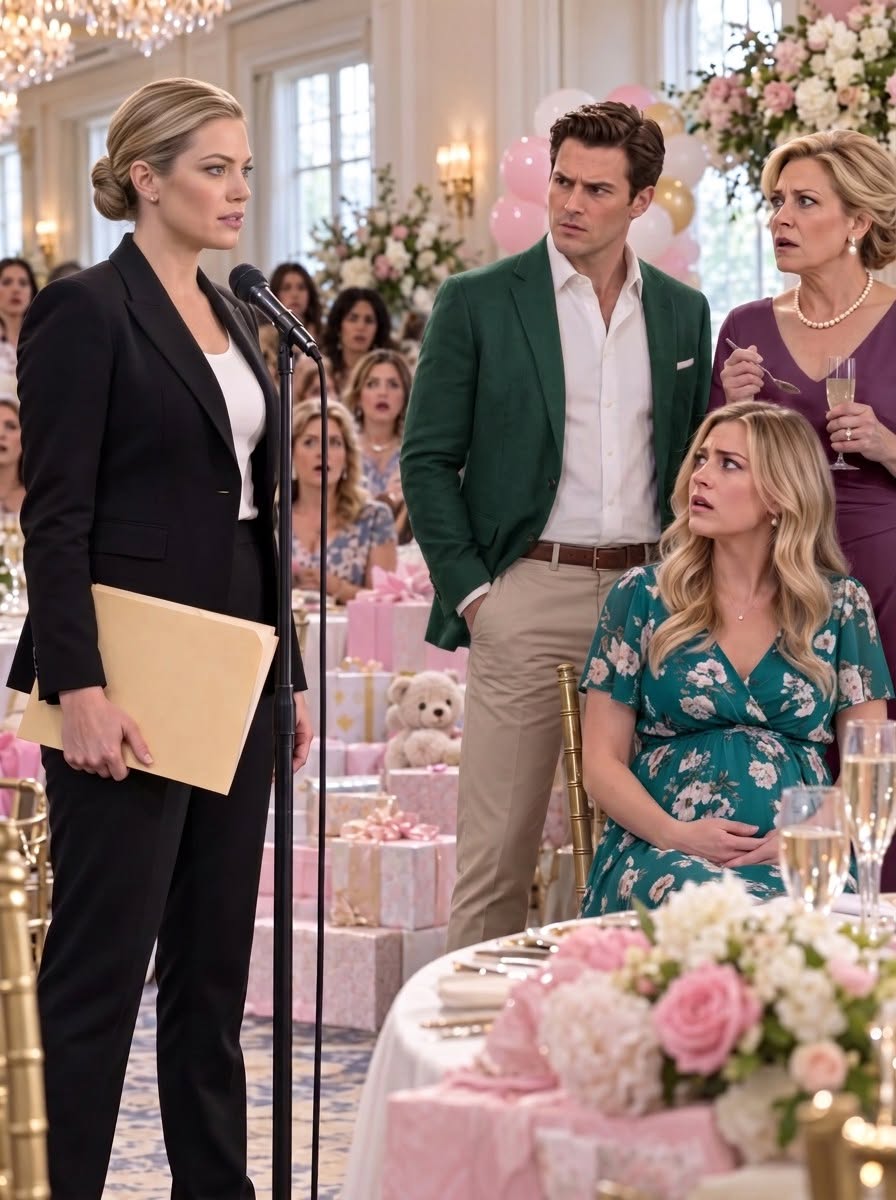
“No,” Harper said, voice cracking dramatically. “She’s acting like we’re strangers.”
Strangers usually respected boundaries better.
I stood, took a folded $20 bill from my jacket, and placed it beside the wine.
“For dinner,” I said.
Mom stared at it.
“Naomi, sit back down.”
I was already leaving.
Behind me, Harper cried louder. Chase muttered something.
Dad remained silent.
Outside, the cold air cleared my head.
For the first time all week, I wasn’t tired.
I was alert.
Sunday dinner had revealed something important.
Harper and Chase weren’t embarrassed.
They were urgent.
Embarrassed people soften requests and negotiate.
Urgent people jump directly to entitlement because time is running out.
At 7:12 the next morning, I sat at my kitchen counter with coffee and two laptops.
The smell of paint still lingered upstairs.
I stopped treating the situation like family drama.
I treated it like an audit.
County property records.
Credit monitoring.
State business registrations.
My house showed no ownership changes or unauthorized liens.
Then I found several financial verification requests connected to my address while I’d been deployed.
They traced back to Sterling Auto Consulting LLC.
Chase’s company.
Beneath the registration was a commercial loan application filed nineteen days earlier.
Collateralized residential stability verification.
Primary residence: Naomi Vance property address.
I read it three times.
Chase had listed my house as his current residence.
The requested loan amount was 85,420,000 in commercial expansion funding and delinquent balance consolidation.
The nursery suddenly made sense.
His business showed declining revenue, debt restructuring, vehicle inventory losses, and two late commercial lease payments.
The baby wasn’t why they needed my house.
The baby was packaging.
A credit activity report exposed something else.
Three pieces of certified mail had been signed for while I was offshore.
Not by me.
By Evelyn Vance.
My mother.
One came from Ridgeway Commercial Lending, another from a collections attorney, and the third from North Harbor Financial Compliance Services.
She had received financial correspondence tied to my property and said nothing.
I kept digging.
Chase had filed business renewals late twice in eighteen months, and financing was already attached to company inventory.
His commercial loan showed unstable debt-to-income, insufficient liquidity, and conditional approval pending residential verification.
If he could establish stable housing tied to collateral support, he could secure the loan.
My house wasn’t convenient.
It was financially necessary.
Suddenly, Sunday dinner looked like theater.